Satisfying the prevailing wage and apprenticeship (PWA) requirements under Section 48E Clean Electricity Investment Credit can bump credit from a base rate of 6% to a 30% applicable percentage, potentially multiplying credit up to five-times for many projects.
Where claiming this credit can get complicated, though, is in figuring out which projects actually qualify and how that's tracked. Under the final Treasury regulations, PWA compliance for Section 48E is more frequently being tracked by facility rather than project wide.
This blog walks through what the regulations say, where the qualified-facility-level tracking requirement comes from, and where the boundaries of that rule create scrutiny risk.
The Core Rule: A 30% Rate Tied to Facility-Level Compliance
If a qualified facility or energy storage technology (EST) satisfies the categories of § 1.48E-3(b), it may qualify for the increased 30% applicable percentage.
What are the Section 1.48E-3(b) categories? Notably, each category is written in reference to a specific qualified facility or a specific EST rather than a broader project or portfolio. The regulation identifies:
- A qualified facility with a maximum net output of less than one megawatt (the One Megawatt Exception);
- A qualified facility whose construction began prior to January 29, 2023;
- A qualified facility that satisfies the prevailing wage, apprenticeship, and associated recordkeeping requirements. (See § 1.48E(d)(3), § 1.45-7, § 1.45-8, and § 1.45-12)
- An EST with a capacity of less than one megawatt (the EST One Megawatt Exception);
- An EST whose construction began before January 29, 2023; or
- An EST that satisfies the parallel prevailing wage, apprenticeship, and recordkeeping requirements described in paragraph (3).
From a compliance perspective, the message is straightforward: each qualified facility generally carries its own compliance burden and its own support for claiming the increased credit rate. A taxpayer operating multiple facilities cannot automatically assume that compliance documentation maintained at the project level will be sufficient if scrutiny arises later.
Why This Differs from the Old Section 48 Framework
One area that may create confusion is the assumption that Section 48E follows the same aggregation principles used under the legacy Section 48 investment tax credit. In practice, Treasury and the IRS adopted a much narrower approach.
Historically, Section 48 has allowed multiple energy properties to be treated as part of a broader energy project under certain circumstances. During the regulatory process, several commenters asked Treasury and the IRS to extend a similar concept to Section 48E. Their argument was practical: labor compliance is often administered across an entire project, not by individual facility, making facility-level certification burdensome.
The Treasury and the IRS rejected this. The final rule's preamble states plainly that “[t]he statute requires that each qualified facility satisfy the [PWA] requirements and for this reason the commenter's suggestions cannot be adopted." If a taxpayer doesn't satisfy the PWA requirements for a given qualified facility, the remedy is the correction-payment and penalty mechanism for that facility, not blending its compliance status into a larger group.
At the same time, Treasury and the IRS did not completely eliminate aggregation concepts under Section 48E. Instead, they retained a narrowly tailored aggregation rule tied to a specific purpose: preventing taxpayers from dividing larger facilities into smaller pieces solely to qualify for the One Megawatt Exception. The regulations make clear that this aggregation concept is limited and generally does not extend to other areas of Section 48E, including eligibility analyses for certain bonus credit provisions.
This broader regulatory approach reinforces an important theme throughout Section 48E: facility-level analysis is generally the default unless the regulations specifically provide otherwise.
The One Exception: "Integrated Operations" for the One Megawatt Exception
While facility-level tracking is the general rule, there is one important exception.
The regulations permit certain facilities to be aggregated when determining eligibility for the One Megawatt Exception. This concept is referred to as "integrated operations," and it may be one of the areas most likely to draw IRS scrutiny because it depends heavily on the underlying facts of a project.
Under § 1.48E-3(c)(4), facilities generally may be treated as having integrated operations if they:
- Are owned by the same or related taxpayers;
- Are placed in service during the same taxable year; and
- Transmit electricity through the same point of interconnection or otherwise support the same end user in specified circumstances.
Comparable rules also apply to energy storage technologies.
If facilities satisfy these factors, their capacities may be combined when determining whether they qualify for the One Megawatt Exception. This means a facility that appears to qualify on its own may lose access to the exception once related facilities are aggregated.
The ownership requirement is particularly important. The regulations treat certain commonly controlled businesses as related taxpayers, meaning that simply placing facilities into separate legal entities may not avoid aggregation. The ultimate determination depends on the full facts and circumstances surrounding ownership and control.
For compliance teams, this creates a notable scrutiny risk. A developer may structure a project as several smaller facilities, each below one megawatt, only to discover that the integrated-operations analysis requires those facilities to be evaluated together.
In those situations, documentation regarding ownership structure, placed-in-service dates, and interconnection arrangements may become just as important as prevailing wage records themselves.
Facility-Level Tracking Continues After Construction
The facility-level concept does not end once a credit is claimed.
Several ongoing compliance obligations under Section 48E continue to operate on a facility-by-facility basis.
Alteration and Repair Work
Under § 1.48E-3(e), taxpayers are generally considered to satisfy prevailing wage requirements during a taxable year if no alteration or repair work occurs during the five-year recapture period described in § 1.48-13(c)(4).
Because this analysis applies at the qualified-facility level, taxpayers with multiple facilities may need to separately monitor alteration and repair activity for each facility rather than treating an entire portfolio as sharing one compliance timeline.
Correction Payment Relief
The transition relief provisions contained in § 1.48E-3(d) were also administered at a granular level. Relief from certain correction-payment penalties depended on factors tied to individual workers and facilities rather than portfolio-wide determinations.
Together, these provisions suggest that ongoing PWA compliance monitoring should remain organized around the individual facility whenever possible.
Applicability Date
The rule applies to qualified facilities and qualified ESTs placed in service in taxable years ending after January 15, 2025, and the construction of which begins after March 17, 2025. Taxpayers may elect to apply the section early to facilities placed in service in taxable years ending on or after January 15, 2025, with construction beginning before that date, provided they follow the section in its entirety and in a consistent manner. That "entirety and consistency" condition is notable in that the regulatory text suggests a taxpayer should not selectively apply favorable pieces of § 1.48E-3 to one facility while relying on prior guidance for another within the same portfolio.
What We're Seeing: What Makes a "Qualified Facility"?
A wide range of groups have approached their interpretation of this differently, and much of that comes down to how a firm draws the boundaries of a single qualified facility.
Some firms have opted to enforce the strictest possible reading, taking an aggressive approach as a preventative measure. One example we've seen is with a clean energy project with multiple inverters. Because eligibility for the One Megawatt Exception (and PWA obligations more broadly) is measured at a qualified-facility level, some firms treat each inverter as its own qualified facility and apply prevailing wage requirements to each inverter individually rather than the project as a whole. Under this approach, a project with several inverters, each above the one-megawatt threshold on its own, would need prevailing wage compliance tracked and documented inverter by inverter, even though every inverter sits on the same site and is part of the same overall development.
Other firms have taken the opposite view, applying prevailing wage requirements to the project as a whole rather than segmenting compliance by individual inverter. These firms generally point to the practical realities of labor administration: payroll, contracting, and workforce management are typically already organized at the project level, and facility-by-facility documentation can be layered onto that structure rather than replacing it.
Ultimately, each end of the spectrum carries its own trade-offs. Regardless of the approach, our experts are trained to assist with navigating prevailing wage requirements at all levels. If you're seeking assistance with compliance, we may have the solutions for you.
Practical Considerations for Compliance Teams
For many organizations, the real challenge can come in implementing processes that align with how the IRS may evaluate compliance. While every project is unique, the following considerations may help identify areas that warrant closer review:
Organize Records by Qualified Facility
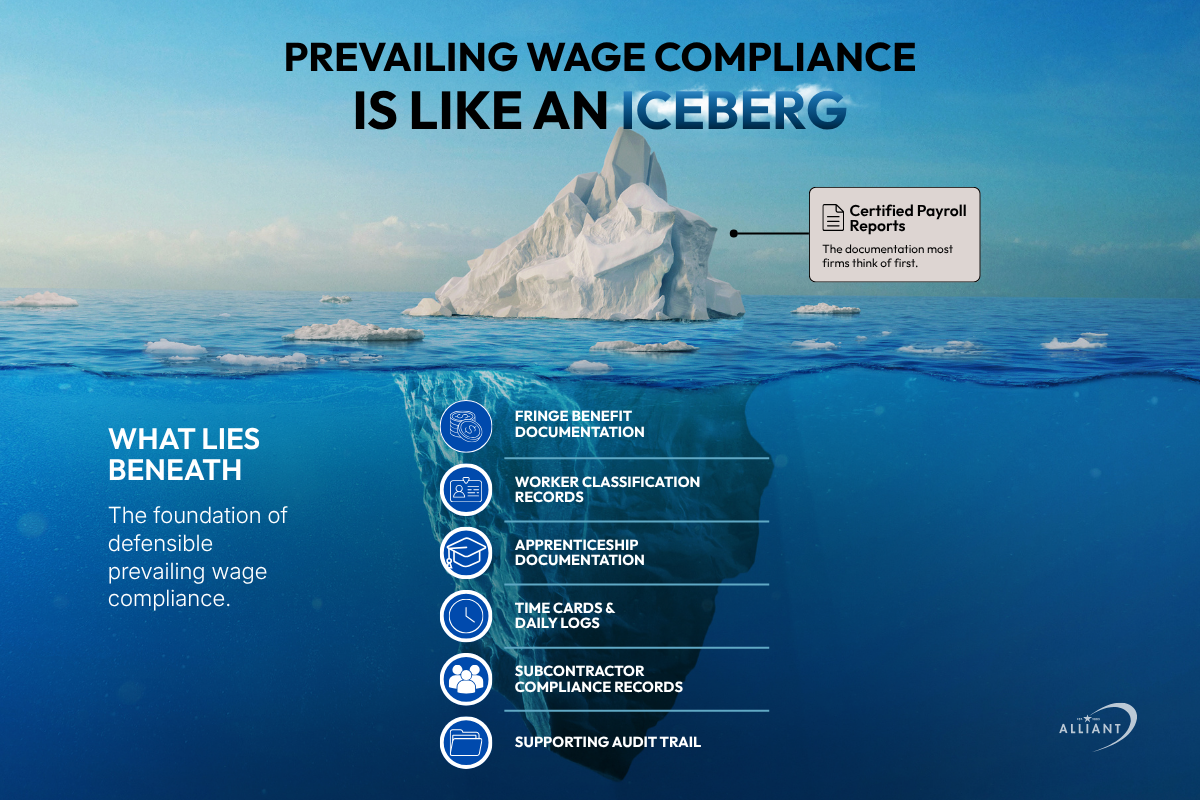
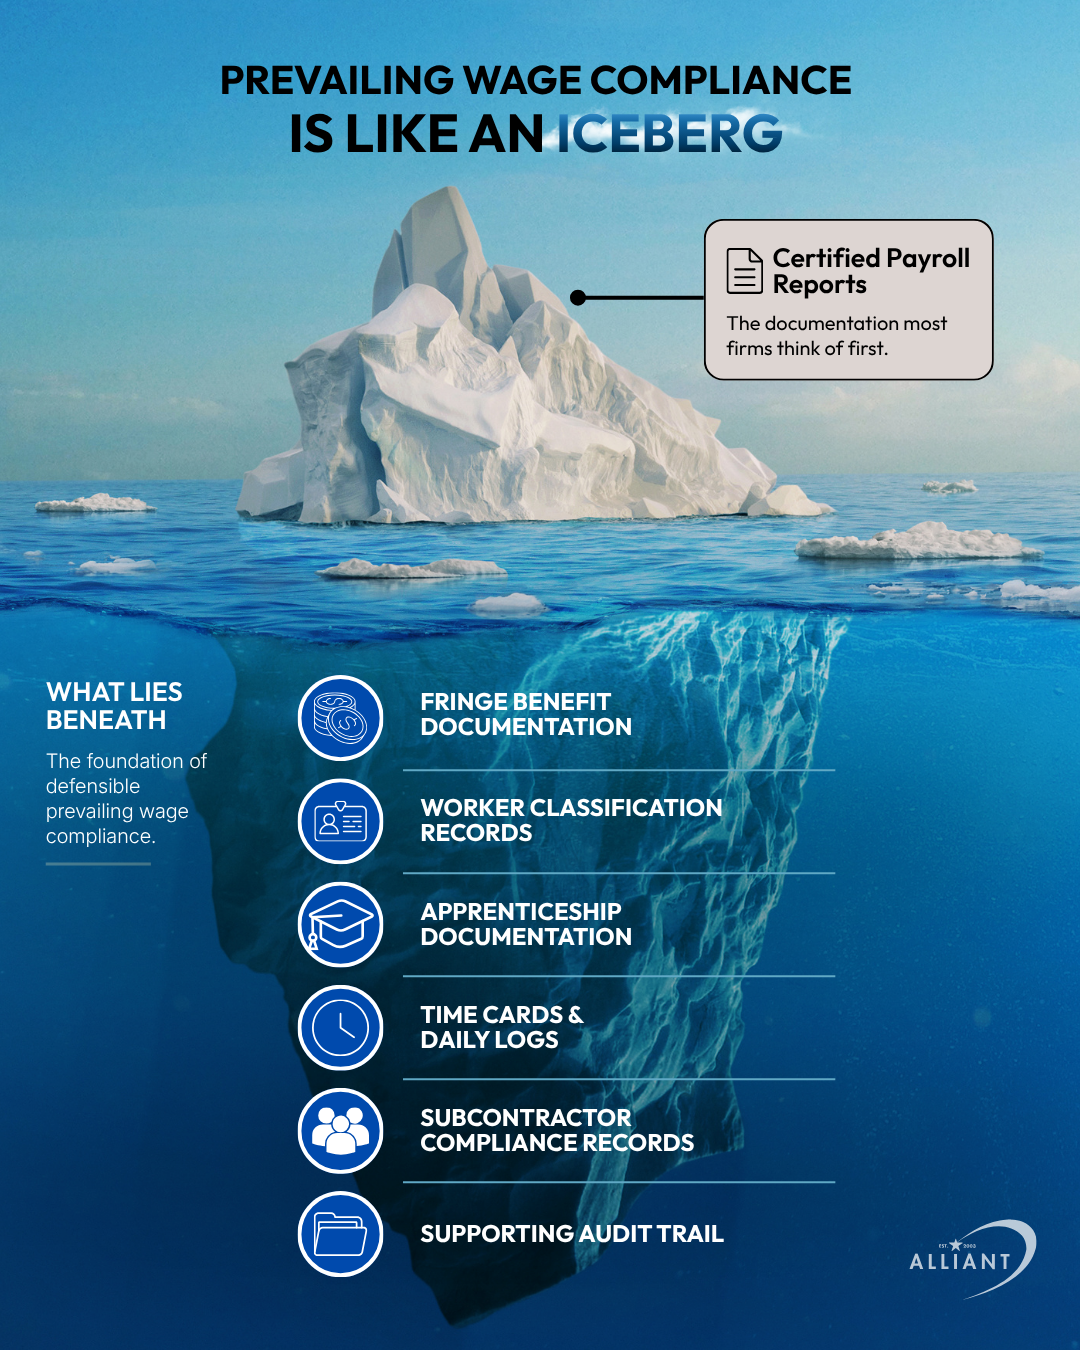
Certified payroll records, apprenticeship documentation, wage determinations, and correction-payment support may better substantiate the credit requirements if they can be produced on a facility-by-facility basis rather than as a single project-wide package.
Evaluate Integrated-Operations Exposure Early
Projects involving multiple facilities under common ownership should evaluate integrated-operations considerations before relying on the One Megawatt Exception, particularly where facilities share interconnection points or are placed in service during the same taxable year.
Track Recapture Periods Separately
Facilities within the same portfolio may have different placed-in-service dates and different compliance timelines. Tracking recapture periods separately can help reduce confusion about ongoing PWA obligations.
Review Applicability Dates Carefully
Projects that began construction before March 17, 2025 may be subject to transition considerations that affect which regulatory framework applies. Those decisions are often easier to address early than after a credit position has been established.
Don't Assume Section 48 Rules Carry Over
Teams familiar with legacy Section 48 aggregation principles should confirm whether those concepts actually apply under Section 48E. In many situations, the answer may be different than expected.
Project-Wide Contracts May Not Be Enough
Even when labor is contracted and managed across an entire project, Treasury and the IRS have made clear that each qualified facility must independently satisfy the PWA requirements. Documentation that clearly links workers and compliance records back to specific facilities may provide stronger support during an examination.
Conclusion
The final Section 48E regulations send a consistent message: PWA compliance is generally evaluated one qualified facility at a time.
That distinction becomes especially important for developers managing multi-facility portfolios, facilities approaching the One Megawatt Exception threshold, or projects with staggered construction and placed-in-service dates.
As clean energy projects continue to grow in size and complexity, documenting how each facility was evaluated under § 1.48E-3, including any integrated-operations analysis, are key practices alongside maintaining the underlying wage and apprenticeship records. If you have questions about how these rules can appear on your project, our team is available to provide prevailing wage compliance guidance and support. Reach out today.