Categories
blog

What is a Classification?

The contents of the following blog come from our YouTube video.

For firms that are new to prevailing wage, understanding the terminology used on public works projects is an important first step toward compliance. One of the most common terms contractors encounter is classification. But what exactly does a classification mean, and how does it determine the wage rate an employee should receive?

A classification, sometimes called a “craft” or a “trade,” identifies the specific type of skilled work being performed on a public works project. Understanding how classifications work can help contractors determine the correct prevailing wage rate and avoid potential compliance issues.

What is a Classification?

A classification is the specific type of work being performed by a worker on a prevailing wage project. Common classifications include Laborer, Electrician, Carpenter, and Operating Engineer.

When determining the appropriate prevailing wage classification, the work being performed is more important than an employee’s job title. Prevailing wage is generally based on the actual work being performed rather than what appears on an employee’s business card, job title, or paycheck stub.

This distinction is important because two workers with the same job title may need to be paid under different classifications depending on the work they perform.

For example, consider a worker who is digging trenches and moving materials by hand. That work may typically fall under a Laborer classification. If that same worker operates an excavator to perform the digging, the work has changed and may instead fall under an Operating Engineer classification.

The tasks being performed determine the classification.

Classifications Can Be Further Divided by Work Performed

Some classifications may be divided into additional groups based on the specific type of work being performed within a trade.

For example, a Laborer who is shoveling asphalt may fall under a different group than a Laborer performing traffic control. Although both workers may generally be considered Laborers, the specific duties they perform can affect the applicable classification.

This is why it is important to look beyond an employee’s general job title when determining the appropriate classification for a prevailing wage project.

Why Do Classifications Matter for Prevailing Wage Compliance?

Correctly classifying is an important part of determining the correct prevailing wage rate for a worker.

A prevailing wage determination generally provides wage rates for different classifications of laborers and mechanics. Contractors must identify the classification that corresponds with the work their employees are actually performing in order to determine the applicable wage rate.

A mismatch between the work being performed and the classification being reported can create compliance issues. For example, if an employee is paid under a lower-tier classification while actually performing higher-skilled or differently scoped work, the employee may not be receiving the appropriate wage rate.

Misclassification is one of the issues that can arise during certified payroll audits.

Accurate classification also plays an important role in payroll reporting and recordkeeping. Maintaining documentation that supports the work employees performed can help demonstrate why a particular classification was used.

Classification and Certified Payroll

Classification is also reflected in certified payroll reporting. When employees work on projects subject to prevailing wage requirements, their classification is part of the information used to document their wages and hours.

Keeping accurate timecards and descriptions of the work performed can help support proper classification. This becomes especially important when an employee is capable of performing work across multiple trades or classifications.

For example, an employee may perform work exclusive to a Laborer classification on one day and work exclusive to a Carpenter classification on another day. The employee may therefore be reported under the applicable classification for the work performed on each day.

Accurate records provide supporting documentation for the classifications reported on certified payroll.

What Is the Connection Between Classification and Wage Rates?

Once the appropriate classification has been identified, it becomes a starting point for determining the correct prevailing wage rate for the project.

Prevailing wage determinations can include different rates for different classifications. The applicable rate may also include additional requirements, such as fringe benefits or other provisions associated with the classification.

Because of this, selecting the correct classification is more than simply choosing a job title. It is an important step in determining the amount an employee may be owed.

Conclusion

A classification is defined by the work being performed, not simply by the worker’s job title. Sometimes referred to as a craft or trade, a classification identifies the type of work being performed and serves as a starting point for finding the correct prevailing wage rate for a project.

Understanding classifications is an important part of prevailing wage compliance. Contractors should evaluate the actual tasks, tools, skills, and materials involved in the work to help determine the appropriate classification and maintain accurate payroll records.

Have questions about prevailing wage classifications or compliance? Let’s get in touch.

Categories
blog

What is an Awarding Body?

The contents of the following blog come from our YouTube video.

When working on a public works project, contractors will encounter a variety of terms and concepts related to prevailing wage. One of these terms is the “awarding body.” Understanding what an awarding body is and what role it plays on a project can help contractors better understand the requirements they are working under.

What is an Awarding Body?

An awarding body is the public agency that contracts for and oversees a public works project. It is the entity that awards the contract to a contractor and typically holds responsibility for ensuring prevailing wage requirements are followed throughout the life of the project.

Awarding bodies can look different depending on the project. An awarding body may be a city or county government, a school district, a state agency, a transit authority, or a federal agency. In general, it is the public entity that is funding or contracting for the work.

Why Does the Awarding Body Matter?

Understanding who the awarding body is matters for several reasons.

First, the awarding body is often a contractor’s point of contact for project-specific requirements. These requirements can include which wage determination applies, reporting procedures, and local or program-specific rules that are layered on top of standard prevailing wage requirements.

Understanding the applicable wage determination is particularly important because it identifies the classifications and wage rates that apply to the project.

Second, awarding bodies frequently have compliance monitoring responsibilities. This can include reviewing certified payroll records, responding to complaints, and, in some cases, referring violations to the appropriate labor agency for enforcement.

Because certified payroll records are an important part of prevailing wage compliance, contractors should make sure their payroll information accurately reflects the work performed and wages paid.

Awarding Body vs. Funding Source

The awarding body is not always the same entity as the funding source.

A project can be funded through a state or federal program but administered locally. In these situations, it is important to understand who is actually awarding and overseeing the contract versus who is providing the funding.

This distinction between the funding source and awarding body comes up frequently on state- and federally funded projects. Contractors should identify the awarding body early in the project rather than assuming that the organization providing the funding is also the entity responsible for awarding and overseeing the contract.

Understanding the Awarding Body’s Requirements

Knowing who the awarding body is can help contractors understand exactly whose rules and requirements they are working under.

The awarding body may provide information about project-specific wage requirements, reporting procedures, and other compliance obligations. It may also be involved in monitoring compliance throughout the life of the project.

For contractors working on public works projects, identifying the awarding body early can provide a clearer understanding of where project requirements come from and who is responsible for overseeing them.

Conclusion

An awarding body is the public agency that contracts for and oversees a public works project. It is the entity that awards the contract to the contractor and typically oversees prevailing wage compliance throughout the project.

Awarding bodies can include cities, counties, school districts, state agencies, transit authorities, and federal agencies. They may also have responsibilities related to project-specific requirements and compliance monitoring.

It is also important to distinguish the awarding body from the project's funding source, since the entity providing the funding is not necessarily the entity awarding or administering the contract.

Understanding who the awarding body is early in a project can help contractors identify the rules, reporting procedures, and prevailing wage requirements they are expected to follow.

Have questions about prevailing wage requirements? Let’s get in touch.

Categories
blog

Notice 2025-42 Is Vacated: What the Restoration of the 5% Safe Harbor Means for Wind and Solar Projects and Their Prevailing Wage Compliance

On June 6, 2026, the U.S. District Court for the District of Columbia vacated IRS Notice 2025-42 in full, ruling it "arbitrary and capricious" under the Administrative Procedure Act (APA). The decision in Oregon Environmental Council v. IRS, Civil Action No. 1:25-cv-04400 (CKK) (D.D.C. June 6, 2026), restored a beginning-of-construction framework just weeks before the OBBBA's July 4, 2026 beginning-of-construction deadline.

Quick Summary/Timeline

  • The Inflation Reduction Act (IRA) of 2022 created the Section 45Y clean electricity production tax credit and Section 48E clean electricity investment tax credit as technology-neutral incentives for zero-emission electricity generation.
  • The One Big Beautiful Bill Act (OBBBA), enacted July 4, 2025, accelerated the phase-out of these credits for wind and solar, requiring projects to begin construction by July 4, 2026 (or be placed in service by December 31, 2027) to preserve credit eligibility.
  • Since 2013, "beginning of construction" has generally been established through one of two methods: the Physical Work Test or the Five Percent Safe Harbor.
  • In August 2025, the IRS issued Notice 2025-42, eliminating the Five Percent Safe Harbor for wind projects and most solar projects (over 1.5 MW), leaving the Physical Work Test as the sole method for those facilities.
  • On June 6, 2026, the court vacated Notice 2025-42 in full, restoring the Five Percent Safe Harbor as an available method ahead of the deadline.
  • As of this writing, no appeal or stay has been publicly confirmed, though one remains widely expected among firms tracking the case. The July 4, 2026 beginning-of-construction deadline has now passed.

What does this mean for firms? For the roughly nine-month window between the ruling and the July 4, 2026 deadline, developers had two paths to establish beginning of construction rather than one. Projects that didn't lock in a beginning-of-construction position by that date now proceed on the December 31, 2027 placed-in-service pathway instead. Either way, prevailing wage and apprenticeship (PWA) compliance remains a separate, ongoing requirement regardless of which beginning-of-construction method a project used.

Full Background

What Are Sections 45Y and 48E?

The Inflation Reduction Act of 2022 (Pub. L. 117-169) added Sections 45Y and 48E to the Internal Revenue Code as technology-neutral successors to the older Section 45 production tax credit and Section 48 investment tax credit. Section 45Y provides a production tax credit for electricity generated at a "qualified facility" with a greenhouse gas emissions rate of zero or below; Section 48E provides an investment tax credit based on a taxpayer's qualified investment in such a facility. Both credits apply to facilities placed in service after December 31, 2024.

What Is "Beginning of Construction," and Why Does It Matter?

Neither the IRA nor the OBBBA defines "beginning of construction" in the statutory text. Instead, the IRS has filled that gap through a long series of sub-regulatory notices dating back to Notice 2013-29, which first established the two methods described below. That framework was reaffirmed and extended across more than a decade of subsequent guidance, including Notice 2022-61, which applied the same principles to Sections 45Y and 48E, and, importantly, to the prevailing wage and apprenticeship (PWA) rules discussed later in this post.

"Beginning of construction" matters because it is the trigger date used throughout federal energy tax credit law to determine which set of rules, and which deadlines, apply to a given project.

The Two Tests: Physical Work Test and Five Percent Safe Harbor

Physical Work Test. Construction begins when "physical work of a significant nature" starts. This is a qualitative, facts-and-circumstances test. It focuses on the nature of the work, not its cost or quantity, and covers both on-site work (e.g., excavating a foundation, setting anchor bolts, installing racking) and off-site work performed under a binding written contract (e.g., manufacturing of components, mounting equipment, transformers). Preliminary activities, like planning, permitting, site clearing, and geotechnical testing do not count.

Five Percent Safe Harbor. Construction is deemed to have begun once a taxpayer pays or incurs 5% or more of the total cost of the facility. This is a quantitative, bright-line test that lets developers establish eligibility through early-stage spending, such as procurement or deposits, without needing to show that physical construction activity has actually started on-site.

Both methods have historically been subject to a Continuity Requirement: the taxpayer must maintain continuous progress toward completion, which is generally deemed satisfied under a Continuity Safe Harbor if the facility is placed in service within four calendar years of the year construction began.

Notice 2025-42

The Executive Order Behind It

On July 7, 2025, President Trump issued Executive Order 14315, Ending Market Distorting Subsidies for Unreliable, Foreign-Controlled Energy Sources (90 Fed. Reg. 30,821). The order directed the Treasury Department, within 45 days of the OBBBA's enactment, to issue guidance ensuring that the OBBBA's credit termination provisions for wind and solar were "strictly" enforced, including guidance to prevent taxpayers from using broad safe harbors to establish beginning-of-construction status without having actually built a substantial portion of the facility.

What the Notice Did

In response, the IRS issued Notice 2025-42 on August 15, 2025. The notice:

  • Eliminated the Five Percent Safe Harbor for all wind facilities and solar facilities exceeding 1.5 MW (AC), leaving the Physical Work Test as the sole method available to establish beginning of construction for those projects ahead of the July 4, 2026 deadline.
  • Preserved the Five Percent Safe Harbor only for "low output" solar facilities — those with a maximum net output of 1.5 MW or less.
  • Applied retroactively to any applicable wind or solar facility whose construction had not already begun (under prior guidance) before September 2, 2025.
  • Left the four-year Continuity Safe Harbor in place but effectively required continuity to be shown through actual physical work rather than through the broader "continuous efforts" concept available to Five Percent Safe Harbor projects under prior guidance.

Source: IRS Notice 2025-42, 2025-36 I.R.B. 351 (full text, IRS.gov).

Court Ruling Overturns Notice 2025-42

The Case

Seven governmental, tribal, and private organizations, including the Oregon Environmental Council, sued the IRS, arguing that Notice 2025-42 was arbitrary and capricious under the APA. Seventeen states and the District of Columbia also filed an amicus brief in support of the plaintiffs, arguing the notice would raise electricity costs and disrupt state energy planning.

Source: Amicus Curiae Brief of Oregon et al., Case No. 1:25-cv-04400-CKK, Doc. 29 (D.D.C. Feb. 20, 2026) (full text).

The Holding

On June 6, 2026, Judge Colleen Kollar-Kotelly of the U.S. District Court for the District of Columbia granted the plaintiffs' motion for summary judgment and vacated Notice 2025-42 in full, remanding the matter to the IRS. The court held that the IRS had failed to satisfy the "reasoned decision-making" standard required of federal agencies under Motor Vehicle Manufacturers Association v. State Farm Mutual Automobile Insurance Co., 463 U.S. 29 (1983).

The Practical Effect

With Notice 2025-42 vacated, the pre-existing framework under Notice 2022-61 and its predecessor notices is restored. Wind and large-scale solar developers may once again use either the Physical Work Test or the Five Percent Safe Harbor to establish beginning of construction ahead of the July 4, 2026 deadline.

Two deadlines remain unchanged by the ruling and are worth keeping straight:

  • July 4, 2026: The statutory beginning-of-construction deadline under the OBBBA. Projects that begin construction on or before this date lock in the original phase-out schedule for the 45Y/48E credits.
  • December 31, 2027: The fallback placed-in-service deadline. Projects that do not meet the July 4, 2026 beginning-of-construction deadline are not automatically ineligible for the credits, but they must instead be placed in service by December 31, 2027 to qualify.

Ongoing Developments

As of this writing (July 13, 2026), the July 4 deadline has passed, and this remains a live legal question rather than settled law:

  • No appeal or stay has been publicly confirmed as of this writing, though industry counsel widely expects the government to appeal or seek a stay. The court itself acknowledged in its opinion that there was "almost zero chance" appellate proceedings would conclude before the July 4, 2026 deadline — a prediction that has held true, since the deadline passed with no appellate resolution.
  • This ruling is specific to Sections 45Y and 48E beginning-of-construction timing. It does not address other requirements tied to different guidance or deadlines, such as the "Foreign Entity of Concern" (FEOC) / Prohibited Foreign Entity beginning-of-construction rules, which are anchored by statute to a different, fixed set of pre-2025 notices and are unaffected by this decision.
  • PWA requirements are untouched. The prevailing wage and apprenticeship rules, and the beginning-of-construction concept used to assess whether a project is exempt from them, derive independently from Notice 2022-61 and are not the subject of this litigation.

Given this, several firms tracking the case advised developers not to abandon Physical Work Test documentation even if they qualified under the Five Percent Safe Harbor in the run-up to the deadline, since a later reversal on appeal could still leave safe-harbor-only projects exposed retroactively.

Best Practices — Especially for Prevailing Wage Compliance

Whichever beginning-of-construction method your project ultimately relies on, prevailing wage and apprenticeship compliance is a separate, independent requirement that determines whether you receive the base credit rate or the enhanced rate — generally five times higher — under Sections 45Y and 48E. That determination is not affected by Oregon Environmental Council v. IRS. With that in mind, firms should consider the following:

  • Don't let the safe harbor question distract from PWA documentation. Whether your project qualifies under the Physical Work Test or the Five Percent Safe Harbor, you still need contemporaneous records establishing that laborers and mechanics were paid at least the applicable prevailing wage rates, and that the required percentage of total labor hours was performed by registered apprentices (generally 15% for projects that began construction after December 31, 2023).
  • Document both begin-construction pathways where feasible. If your project can support both a Physical Work Test position and a Five Percent Safe Harbor position, maintain records for both. This creates a fallback if the safe harbor is stayed or reversed on appeal.
  • Track prevailing wage determinations by classification and geography. Rely on published Department of Labor wage determinations (available via SAM.gov), and request supplemental wage determinations promptly if a classification isn't listed for your project's location.
  • Maintain "good faith effort" documentation for apprenticeship requirements. If registered apprenticeship programs deny your request or fail to respond within the required window, keep the request and denial (or non-response) on file — this is what substantiates the good-faith exception.
  • Prepare for Form 7220. Compliance (or correction of a prior failure) is reported using IRS Form 7220, Prevailing Wage and Apprenticeship (PWA) Verification and Corrections. Build your recordkeeping process now so you aren't reconstructing payroll and apprenticeship data under time pressure later.
  • Consult legal counsel before finalizing your beginning-of-construction strategy. With the July 4, 2026 deadline now passed, firms should confirm with legal counsel which beginning-of-construction method their project ultimately relied on and whether that position is well-documented enough to withstand IRS scrutiny or a later reversal on appeal.

Conclusion

The vacatur of Notice 2025-42 is a meaningful change for wind and solar developers racing toward the July 4, 2026 beginning-of-construction deadline. It restores optionality that many projects were built around, but the government's potential for evolution in the legal landscape means rulings could still shift past the deadline.

What remains applicable is the importance of rigorous, well-documented prevailing wage and apprenticeship compliance. Building the foundation for securing the full value of the 45Y and 48E credits is key, regardless of how the begin-construction question is ultimately resolved.

Have questions about how this affects your project's compliance strategy? Connect with our team to make sure your prevailing wage and apprenticeship documentation is airtight, regardless of which safe harbor you rely on to establish beginning of construction.

Categories
blog

Alteration & Repair Under the Inflation Reduction Act: The Compliance Distinction Project Owners Can’t Afford to Ignore

As taxpayers continue to pursue enhanced clean energy tax credits under the Inflation Reduction Act (IRA), many have become familiar with the prevailing wage and apprenticeship requirements that apply during project construction. What remains less understood is how prevailing wage obligations apply after a facility has been placed in service.

The IRA expressly requires prevailing wage compliance not only during construction, but also during certain post-construction activities. Specifically, taxpayers seeking enhanced credit amounts must ensure that laborers and mechanics performing “the alteration or repair of such facility” are paid prevailing wages during the applicable compliance period. (Federal Register, TD 9998)

For owners, developers, EPC contractors, and operations teams, the challenge is determining when routine operations and maintenance (O&M) activities cross the line into alteration or repair work that may trigger prevailing wage obligations.

Why This Distinction Matters

The financial consequences of getting this classification wrong can be significant. For many IRA incentives, taxpayers that satisfy the applicable prevailing wage and apprenticeship requirements can receive a credit amount that is up to five times greater than the otherwise applicable base credit.

At the same time, taxpayers that fail to satisfy prevailing wage requirements may be required to make correction payments, pay penalties, and work through statutory cure procedures to preserve eligibility for enhanced credit values.

As a result, understanding whether post-construction work constitutes routine maintenance or a covered alteration or repair is an important compliance consideration.

Some Interpretation Background Between the IRS and DBA

One of the most important observations from Treasury’s final regulations is that the agencies acknowledged the challenges of applying Davis-Bacon concepts traditionally used in federal contracting to a tax-credit framework.

In the preamble to the final regulations, Treasury and the IRS explained that they would incorporate only those Davis-Bacon requirements that are:

relevant for the purposes of section 45(b)(7)(A) and the intent of the IRA, and necessary for, and consistent with, sound tax administration.

Federal Register, TD 9998

The agencies further noted that they must:

take a reasonable approach to interpret a Code provision that references a Federal law applicable to Federal contracts.

For taxpayers and contractors, this language demonstrates that prevailing wage compliance under the IRA often requires a fact-specific analysis grounded in both IRS and Davis-Bacon principles.

What Does the IRS Mean by “Construction, Alteration, or Repair”?

The IRS has specifically addressed the question of what constitutes “construction, alteration, or repair” for purposes of the IRA prevailing wage requirements through its published guidance and FAQs.

Notably, the statute references “the construction of such facility” and “the alteration or repair of such facility.”

What the statute does not specifically reference is routine operations and maintenance. That omission is where much of the compliance analysis begins.

Operations & Maintenance vs. Alteration & Repair

Neither the IRA statute nor the IRS’s prevailing wage regulations provide an exhaustive list of activities that automatically qualify as operations and maintenance (O&M) or alteration and repair (A&R). As a result, taxpayers often look to Davis-Bacon authorities and Department of Labor guidance for interpretive context.

Importantly, the examples below are not definitive legal determinations and should not be interpreted as IRS-approved classifications. Rather, they reflect factors discussed in Department of Labor guidance that may help inform a project-specific analysis.

Activities Often Associated with Routine Maintenance

The Department of Labor has stated that:

Maintenance work that is routinely and regularly performed to keep the building or work functioning in the same condition is not considered construction.

Consistent with that principle, activities such as the following may be indicative of routine maintenance when performed to preserve existing operating conditions:

  • Routine inspections and monitoring of equipment performance
  • Preventive maintenance programs performed on a recurring schedule
  • Cleaning and servicing activities intended to maintain existing functionality
  • Minor upkeep work completed repeatedly over time as part of normal facility operations

The Department of Labor has further indicated that maintenance work is often characterized by activities that are “performed continuously/repetitively over time,” “completed comparatively quickly,” and intended to maintain a facility “in its existing condition.”

Activities That May Suggest Alteration or Repair

By contrast, Department of Labor guidance explains that:

Restoration or improvement of a facility by modifications to the facility’s components, systems, or materials is considered to be alteration or repair.

The guidance also notes that alteration or repair work will generally “improve the building or work, either by fixing something that is broken or by improving upon the building or work’s existing condition.”

Based on those principles, activities such as the following may warrant closer review:

  • Major component replacement projects
  • Equipment refurbishments or overhauls that restore or improve facility functionality
  • Modifications to facility systems or materials intended to improve efficiency, capacity, usefulness, or performance
  • Corrective work addressing specific failures, defects, or broken equipment
  • Work requiring skills commonly associated with construction trades

The Department of Labor identifies additional factors suggesting alteration or repair, including whether the work:

  • Corrects “individual problems or defects as separate and segregable incidents,”
  • Improves a facility’s “structural strength, stability, safety, capacity, efficiency, or usefulness,” or
  • Involves skills “typical of one or more construction trades.”

Important Caveat

Ultimately, neither the IRA nor current IRS guidance establishes a simple checklist for determining whether a particular activity constitutes maintenance or alteration and repair. Classification is often highly dependent on the scope, purpose, frequency, and technical nature of the work being performed. Taxpayers should evaluate significant post-construction activities based on the specific facts and circumstances of the project and should consult qualified legal, tax, and prevailing wage advisors when uncertainty exists.

Conclusion

As guidance continues to develop, taxpayers should carefully evaluate significant post-construction activities and document the basis for their classifications to help mitigate compliance risk and preserve enhanced credit eligibility. If questions arise regarding the application of prevailing wage requirements to your project, our team is available to provide experienced guidance and support. Access expert help and reach out today.

Categories
blog

California SB 35: What Contractors Need to Know About Prevailing Wage & Compliance

California Senate Bill 35 (SB 35) reshaped the approval process for multifamily housing developments by introducing a streamlined, ministerial approval pathway for qualifying projects. While the bill is primarily viewed through a housing development lens, it carries significant compliance implications for contractors, especially those operating in the prevailing wage space.

Below is a practical guide to SB 35 focused on what contractors, subcontractors, and compliance teams need to know to stay compliant and audit ready.

Important Update: SB 35 Was Extended and Amended by SB 423

Before diving into compliance details, it’s worth flagging a development that changes how this law should be understood today: SB 35 is no longer a standalone statute operating on its original 2017 terms.

In October 2023, Governor Newsom signed SB 423 (Wiener), which took effect January 1, 2024, and substantially amended the streamlined ministerial approval process originally created by SB 35 (codified at Government Code § 65913.4). Some jurisdictions and planning departments now refer to the process as “SB 423 (formerly known as SB-35).”

Key changes contractors should know about:

  • The sunset date was extended a decade. SB 35 was originally set to expire on January 1, 2026. SB 423 pushed that expiration to January 1, 2036.
  • The old blanket labor standard was replaced with a tiered structure. Previously, SB 35 applied a single objective standard requiring prevailing wage and use of a skilled and trained workforce across covered projects. SB 423 restructured this into size- and height-based tiers (detailed in the Skilled and Trained Workforce section below), rather than a one-size-fits-all requirement.
  • A small-project exemption was added. Projects of 10 units or fewer that are not otherwise a public work are exempt from the prevailing wage, apprenticeship, and healthcare expenditure requirements entirely.
  • The coastal zone exclusion was removed, expanding the geographic reach of projects eligible for streamlined approval.

For contractors and compliance teams, the practical takeaway is this: prevailing wage still applies broadly, but which additional labor standards apply (skilled and trained workforce, apprenticeship utilization, healthcare expenditures) now depends on specific project size and building height thresholds rather than a blanket rule. The sections below reflect the current SB 423-amended framework.

What Is SB 35?

SB 35 allows qualifying multifamily housing projects to bypass discretionary approvals and move through a streamlined, by-right approval process if they meet objective zoning and affordability requirements.

Key features include:

  • Ministerial (non-discretionary) approvals
  • Strict timelines for local agency review (60–90 days depending on project size)
  • Requirements tied to affordability thresholds and housing production goals
  • Applicability to jurisdictions that fall behind on regional housing needs (RHNA)

Prevailing Wage Requirements Under SB 35

SB 35 explicitly ties streamlined approval eligibility to prevailing wage compliance.

When Prevailing Wage Applies

Under SB 35, developers must certify one of the following:

  • The project is a public work, OR
  • All construction workers will be paid at least the general prevailing wage for the applicable trade and location

This applies even when the project is privately funded.

Contractor Responsibilities

For contractors and subcontractors, this means:

  • Paying DIR-determined prevailing wage rates
  • Ensuring apprentices are paid the correct apprentice wage rates
  • Flowing prevailing wage requirements down to all subcontractor tiers
  • Including prevailing wage clauses in all contracts
  • Skilled and Trained Workforce requirements (if applicable)

Failure to comply can lead to:

  • Civil wage and penalty assessments
  • Liquidated damages
  • Enforcement actions by the California Labor Commissioner

Certified Payroll & Recordkeeping Requirements

SB 35 reinforces standard California Labor Code §1776 recordkeeping requirements.

Contractors must maintain and verify certified payroll records, make records available for inspection upon request, and retain documentation sufficient to support reported wages and classifications.

Best Practice: Go Beyond CPRs

As seen in similar compliance frameworks, certified payroll alone is not sufficient for audit protection. Contractors should also maintain:

  • Timecards and daily job logs
  • Worker classification documentation
  • Fringe benefit contribution records
  • Fringe benefit annualization calculations
  • Apprenticeship agreements and ratios
  • Subcontractor compliance documentation

Without these, contractors risk exposure during Labor Commissioner investigations, worker complaints, and potential audits.

Skilled and Trained Workforce (STW) Requirements

Under the pre-2024 version of SB 35, a single objective standard applied broadly across covered projects. SB 423 replaced that with a tiered labor standard based on project size and building height:

  • Projects of 50 or more housing units must meet apprenticeship-utilization and healthcare expenditure requirements for construction craft employees, either directly, or by being signatory to a collective bargaining agreement that already requires both. Each construction contractor must also maintain and verify payroll records pursuant to Section 1776 of the Labor Code, and submit payroll records directly to the Labor Commissioner at least monthly in a format prescribed by the Labor Commissioner in accordance with subparagraph (A) of paragraph (3) of subdivision (a) of Section 1771.4 of the Labor Code.
  • Buildings taller than 85 feet must utilize a skilled and trained workforce and hit certain percentage goals, or face penalties for non-compliance.
  • Projects of 10 units or fewer where the project is not otherwise a public work are exempt from the prevailing wage, apprenticeship, and healthcare expenditure requirements entirely.

What This Means

Rather than assuming a flat STW threshold applies, contractors need to check a given project against its unit count and building height to determine which labor standards apply. A 12-unit, 3-story project and a 200-unit high-rise can trigger very different obligations under the same law. All subcontractors on a covered project are still required to comply with whichever standards apply.

Reporting Obligations

Developers (and often contractors supporting them) must submit monthly compliance reports to the local jurisdiction and demonstrate adherence to STW requirements.

Failure to comply may result in:

  • $10,000/month penalties for missing reports
  • $200/day per non-compliant worker penalties

Subcontractor Compliance: Flow-Down Liability

As with other public works frameworks, SB 35 places responsibility on prime contractors to enforce compliance across all tiers. This includes collecting certified payroll from subcontractors, verifying wage rates and classifications, and ensuring proper contract language is in place.

If a subcontractor fails to comply, liability may flow upstream, particularly where oversight procedures are lacking.

Apprenticeship Requirements

SB 35 aligns with broader California apprenticeship requirements:

  • Proper apprentice-to-journeyman ratios must be maintained
  • Apprentices must be registered in approved programs
  • Wage rates must match applicable prevailing apprentice rates
  • Payment of training amount to applicable program or CAC

Noncompliance in this area is a frequent audit trigger and often overlaps with STW requirements.

Interaction with Other Regulations

SB 35 projects may also intersect with:

California Prevailing Wage (DIR)

Core requirement for all covered work. Includes:

  • Use of wage determinations
  • Public works enforcement framework
  • CPR and recordkeeping obligations

Davis-Bacon (Federally Funded Projects)

If federal funding is involved:

  • Federal prevailing wage requirements may apply concurrently
  • Dual compliance (state + federal) may be required

Section 3 (HUD-Funded Projects)

If HUD funding is used:

  • Hiring and contracting goals for low-income workers
  • Additional reporting and documentation requirements

Project Labor Agreements (PLAs)

If a PLA is in place, some enforcement mechanisms (e.g., payroll record provisions) shift to arbitration frameworks instead of statutory enforcement.

Audit & Enforcement Risk

Scrutiny under SB 35 enforcement can come through the following forms:

  • Public reporting requirements
  • Streamlined approvals tied to compliance certifications
  • Monthly workforce reporting (STW)

Common audit triggers include:

  • Payroll discrepancies
  • Worker complaints
  • Missing documentation
  • Misclassification issues

Penalties can include:

  • Back wages
  • Interest and fines
  • Debarment from future public works

Key Takeaways for Contractors

Contractors should approach these projects with a compliance-first strategy:

  1. Treat all SB 35 projects as high-compliance work. Even if privately funded, prevailing wage can apply.
  2. Strengthen recordkeeping systems. Certified payroll is not enough. Maintain full supporting documentation.
  3. Audit subcontractors proactively. Do not assume compliance. Verify it through every party.
  4. Prepare for Skilled & Trained Workforce tracking. Ensure workforce eligibility and reporting systems are in place.
  5. Align contracts with compliance requirements. Include all mandated language and obligations upfront.

Final Thoughts

Compliance under SB 35 requirements layers prevailing wage, workforce requirements, and reporting obligations. Contractors who succeed under SB 35 will be those who build compliance into project workflows early, maintain a well-documented paper trail of proof of compliance, and actively manage subcontractor risk.

As enforcement continues to evolve, partnering with experienced prevailing wage consultants can help ensure your projects stay compliant from bid to closeout. Connect with us to learn how you can get assistance in the compliance process.

Categories
blog

The AI Data Center Boom Meets Prevailing Wage: A State-by-State Look

As the power of AI exponentially scales, data centers go up across the country to house the infrastructure needed for this technology. States have taken notice, and a growing number are attaching strings to that growth: incentives to attract developers, labor standards to protect the workforce doing the building, or both. In a handful of states, those labor standards now include prevailing wage, and in some cases, apprenticeship requirements.

If your firm works in data center construction, or is considering it, here’s what’s already law, what’s moving through statehouses right now, and how to think about compliance in a sector that didn’t traditionally think of itself as “public works.”

Why Data Centers, and Why Now

Data centers are not new, but the scale of what’s being built is. A single large-scale AI training facility can draw as much electricity as a mid-sized city, and utilities, grid operators, and state legislatures are all racing to catch up. That’s created two distinct regulation types in state legislatures:

  1. Incentive-driven bills, aimed at attracting data center investment (tax exemptions, streamlined permitting, dedicated electricity rate structures).
  2. Labor-standards bills, aimed at ensuring that the construction workforce building these facilities (often on an accelerated, high-dollar timeline) is paid fairly and trained properly.

Some legislation does both at once: offering a tax benefit or rate structure in exchange for labor commitments on the construction side. That pairing is exactly what’s driving the prevailing wage trend below.

If you’re already tracking clean energy prevailing wage triggers under the Inflation Reduction Act, this will feel familiar. Data centers are becoming the AI-era version of the same policy pattern: big federal or state incentive, paired with a labor standards string attached.

States That Have Passed Data Center Prevailing Wage Requirements

California — SB 978

California’s SB 978 takes a “rate structure plus labor standards” approach. The bill requires the California Public Utilities Commission (PUC) to create a special electricity rate structure for large data centers, defined as facilities primarily processing digital information with a peak demand of at least 75 megawatts. This ensures these facilities pay for the infrastructure upgrades their power demand requires rather than shifting those costs onto other ratepayers. In exchange, large data centers must also contribute to funding new zero-carbon energy resources, and their construction projects must meet specific labor requirements, including paying prevailing wages and using a skilled and trained workforce — effectively treating qualifying data center construction as a public works project. The bill also folds data centers’ impact into the state’s existing tracking toward its 100% clean electricity goal by 2045.

For firms already managing California prevailing wage compliance on public works or renewable energy projects, this extends a familiar framework: skilled and trained workforce documentation, certified payroll, and DIR-aligned prevailing wage rates into a new project type.

Minnesota — SSHF16

Minnesota’s approach again pairs a tax incentive with a labor standard. Under SSHF16, “qualified large-scale data centers” were added to the state’s sales tax exemption for purchases of enterprise information technology equipment and computer software, effective for purchases made after June 30, 2025. In exchange, laborers or mechanics performing work to construct or refurbish qualified large-scale data centers must be paid the prevailing wage rate for their work. See our Minnesota prevailing wage compliance page for the state’s existing framework administered by the Department of Labor and Industry (DLI).

States With Data Center Prevailing Wage Bills In Progress

New Jersey — AB 3611

New Jersey’s Assembly Bill 3611 applies prevailing wage directly to data center construction, without pairing it to a separate incentive program. The bill requires that workers employed in the construction of a data center project be paid not less than the prevailing wage rate for their craft or trade, as determined by the Commissioner of Labor and Workforce Development, for data center construction projects with an electrical capacity of five megawatts or greater annually after construction.

Firms doing construction work in New Jersey should compare this threshold carefully against project specs. Our New Jersey prevailing wage compliance page covers the state’s existing Prevailing Wage Act framework that this bill builds on.

Pennsylvania — HB 2061

Pennsylvania’s HB 2061 ties compliance to an affirmation requirement rather than a size threshold. For construction, expansion, rehabilitation, renovation, or site work of a computer data center beginning on or after July 1, 2025, the bill would require an affirmation. This affirmation must be signed by the authorized executive representing the owner or operator and note that all contractors and subcontractors will pay workers not less than the prevailing minimum wage and benefit rates for each craft or classification, as determined and enforced by the Department of Labor and Industry, consistent with the Pennsylvania Prevailing Wage Act (Act of Aug. 15, 1961, P.L. 987, No. 442). This structure puts direct accountability on the owner/operator, not just the contractors performing the work. See our Pennsylvania prevailing wage compliance page for background on how the state’s existing Prevailing Wage Act operates.

Because these two bills are still in progress, their thresholds, effective dates, and even their prevailing wage provisions could change before passage — or the bills could stall entirely. Always confirm current bill status and text directly through the state legislature’s website before relying on it for a specific project.

What This Means for Contractors and Developers

A few patterns are worth flagging as this trend develops:

  • Thresholds vary widely. California’s trigger is a 75 MW peak demand; New Jersey’s proposed threshold is 5 MW of annual electrical capacity. A project that clears one state’s bar for prevailing wage might not come close in another. Don’t assume a single company-wide policy will work across state lines.
  • Prevailing wage and apprenticeship are increasingly bundled. Across several existing prevailing wage types and incentives already established in federal clean energy tax credits, prevailing wage and apprenticeship requirements may travel together to unlock the largest incentive.
  • Some bills reach owners/operators directly, not just contractors. Pennsylvania’s affirmation requirement puts the compliance obligation on the entity commissioning the project, which changes who needs to be at the table when compliance planning starts.
  • Data centers are being treated as “public works” even when privately financed. California’s SB 978 and Minnesota’s SSHF16 both extend prevailing wage to projects that aren’t publicly funded in the traditional sense. The trigger is the incentive or rate structure the facility receives, not government ownership of the project.

Best Practices for Data Center Construction Compliance

  1. Identify your triggers early, per state. Before bidding or scoping a data center project, confirm whether the state has an applicable law and what its size/capacity threshold is — megawatt peak demand, kilowatt capacity, or annual usage can all serve as triggers, and they aren’t interchangeable.
  2. Build classification and wage determination review into pre-construction. As with any prevailing wage project, confirm the applicable craft classifications and current wage determinations before finalizing labor budgets. Rates can shift for a myriad of reasons, ranging anywhere from changes per publication cycle to specific periods in the year.
  3. Plan for apprenticeship utilization where required. Start engaging registered apprenticeship programs early if applicable, and document good-faith efforts if you encounter denials or non-responses.
  4. Confirm who bears the compliance obligation. Determine whether the law places the burden on the contractor, subcontractor, or the project owner or operator (as in Pennsylvania). This affects contract language, certifications, and who needs sign-off before construction begins.
  5. Maintain certified payroll and recordkeeping from day one. Data center construction timelines are often compressed and high-dollar; retrofitting compliance documentation after the fact is far harder than building it in from the start.
  6. Track legislative developments continuously. This is a fast-moving area. New states are introducing similar bills regularly, and existing bills can be amended as they move through committee. What applies to your project today may look different by the time you break ground.
  7. Loop in compliance experts before you bid. Given how much thresholds and mechanisms vary state to state, a pre-bid compliance review can prevent costly missteps once construction is underway.

Conclusion

Data centers are quickly becoming one of the most active construction sectors in the country, and state legislatures are increasingly treating them the way they’ve long treated other large public-facing infrastructure: with labor standards attached. Whether your state has already passed a prevailing wage requirement for data centers, or has a bill working its way through committee right now, the smart move is to build compliance into your planning early, not after the fact.

Have a data center project in the pipeline and want to know whether prevailing wage or apprenticeship requirements apply? Connect with our team to review your project’s state-specific obligations and make sure your compliance strategy is airtight before you break ground.

Categories
blog

Why Supporting Documentation is Key to Compliant Prevailing Wage Projects

Maintaining supporting documentation is the foundation of prevailing wage compliance. For all those working on a prevailing wage project, including (but not limited to), EPCs, contractors, subcontractors, and engineering firms, proper recordkeeping not only protects companies against costly penalties but also ensures eligibility for lucrative public works projects across federal and state programs.

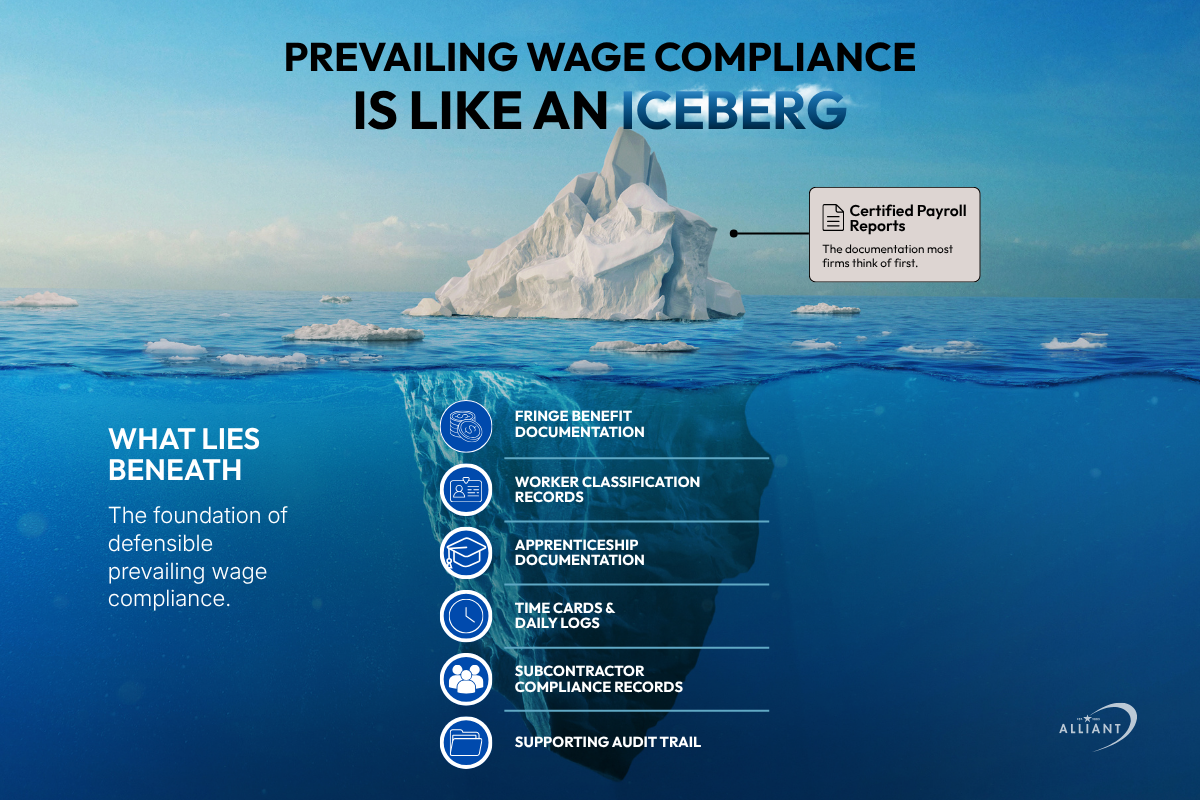
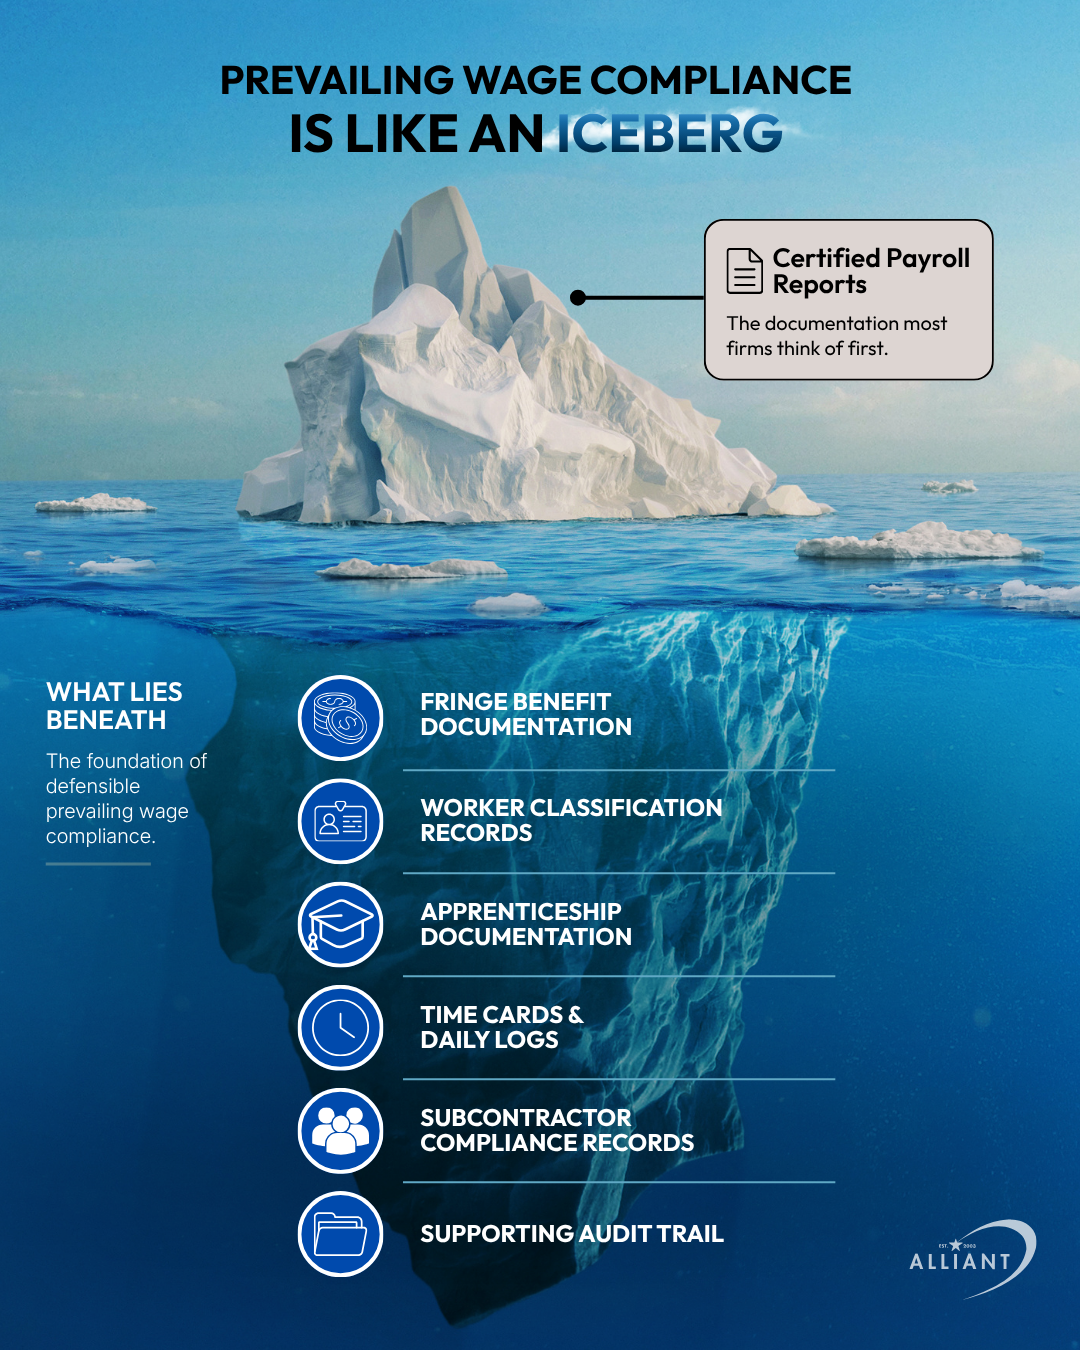
Most know that maintaining payroll records with proper prevailing wage payments is necessary to demonstrate compliance. However, certified payroll reports are only the tip of the iceberg. They summarize wages and classifications, but they don’t stand alone. In the face of a governmental audit, regulators will dig deeper, demanding the supporting documentation that validates every line item. Without it, even unintentional discrepancies can trigger penalties, withheld payments, or disqualification from incentive programs.

Infographic: Prevailing wage compliance is like an iceberg. Certified payroll reports sit above the waterline, while fringe benefit documentation, worker classification records, apprenticeship documentation, time cards and daily logs, subcontractor compliance records, and a supporting audit trail lie beneath.

Why Documentation Matters in Prevailing Wage Compliance

Think of documentation like the seatbelt in your car. Most of the time, you don’t feel its importance. The belt’s just there, quietly strapped across your chest. You might even think, “I’m careful, I don’t really need it.” But the moment an accident happens, whether it’s your fault or not, that seatbelt becomes the single most important thing protecting you from serious harm.

Supporting documentation in prevailing wage compliance works the same way. Day-to-day, it may feel like extra paperwork, especially when certified payroll reports are filed correctly. But if an audit occurs, triggered by a small discrepancy or an unintentional error, those records become your seatbelt. They’re the proof that shields your company from penalties and damage.

What paperwork do I need to prove prevailing wage compliance?

Certified payroll reports are the headline requirement, but they rely on a foundation of supporting records. Examples include, but are not limited to:

  • Fringe Benefit Records: Proof of contributions to health, pension, and training funds.
  • Worker Classification Logs: Documentation that employees are properly classified under wage determinations.
  • Apprenticeship Agreements: Evidence of compliance with apprenticeship ratios and training requirements.
  • Timecards and Daily Logs: Records that validate hours reported on certified payroll.
  • Subcontractor Compliance Records: Documentation showing that lower-tier subcontractors also meet prevailing wage obligations.

These documents are what auditors use to verify the accuracy of certified payroll reports. Without them, the report itself is just numbers on paper.

Getting Assistance with Monitoring Recordkeeping

The examples listed above help cover a big piece of the story, but the list is not exhaustive. The bigger key is ensuring that what is reported on this documentation is all verifiable across each other. When working on a project with several employees for several weeks, months, or years on end, this can be a challenging feat for firms to keep up with. Here, our team steps in to alleviate this burden to complete the review for you. We study prevailing wage and serve to protect firms in the industry from potential penalties that arise in prevailing wage law by supplying our years of experience, technology, and expert team. If you’re interested in seeking assistance with prevailing wage requirements, don’t hesitate to contact our team.

Conclusion

For all firms completing work on prevailing wage projects, compliance can come down to building a trackable paper trail that supports certified payroll reports and proves compliance under scrutiny. No matter what prevailing wage regulation is applicable on a project, supporting documentation is the seatbelt that protects your business in the event of an audit.

Categories
blog

Prevailing Wage & Clean Energy in NY: What Labor Law §224-d Means for Developers & Contractors

Performing construction in New York’s clean energy market? As New York’s clean energy market matures, developers and contractors are encountering a growing set of labor standards. One of the most important, and increasingly relevant, is Labor Law §224-d, a statute that applies prevailing wage requirements to certain renewable energy projects. This blog focuses specifically on §224-d and how wage standards are evolving in the state’s clean energy sector.

How Has Labor Law §224-d Changed?

New York Labor Law §224-d is a state statute that requires construction workers on certain renewable energy projects to be paid prevailing wages, even if the projects aren’t traditional “public works.” In 2022, New York passed legislation, Assembly Bill A.9598 and Senate Bill S.8648, that amended Labor Law §224-d to expand the definition of a “covered renewable energy system.” These bills lowered the system size threshold from 5 megawatts to 1 megawatt or more and clarified that REC procurement by or for a public entity is sufficient to trigger prevailing wage requirements. This expansion significantly broadened the law’s reach, especially for mid-size clean energy projects.

What Triggers Labor Law §224-d?

As amended, Labor Law §224-d requires that workers on certain renewable energy projects be paid prevailing wages, as determined by the New York State Department of Labor (NYSDOL). But unlike traditional public works laws, §224-d is tailored to clean energy and applies when:

  1. The project involves a renewable energy system of 1 megawatt or more, and
  2. The project includes the procurement of renewable energy credits (RECs) by a public entity (or a third party acting on its behalf, such as NYSERDA).

If both conditions are met, the project is considered a “covered renewable energy system” and prevailing wage requirements apply under Article 8 of the Labor Law.

How Labor Law §224-d Growth Affects Developers and Contractors

According to NYSDOL’s July 2024 enforcement guidance, distributed renewable energy systems (like community solar) that are 1 MW or larger (Climate and Community Protection Act, A.9598/S.8648, 2022) and transfer RECs (Renewable Energy Certificates) to investor-owned utilities will now be considered “covered renewable energy systems.” This is because, under a 2025 Public Service Commission order, those RECs will ultimately be purchased by NYSERDA — a public entity whose involvement, even indirectly, is enough to trigger prevailing wage requirements under §224-d.

In other words, once NYSERDA becomes the end buyer of those RECs, regardless of the project’s funding source, the project is treated as publicly supported for labor compliance purposes.

This means that many mid-size projects entering construction in 2025 are now subject to prevailing wage, even if they aren’t directly funded by public dollars.

Who is Affected?

  • Developers of solar, wind, thermal, or offshore wind supply chain infrastructure
  • General contractors and subcontractors performing construction work on qualifying systems
  • Project teams working with NYSERDA or other public REC procurement programs

Even if your project is privately financed, it may still fall under §224-d if RECs are sold to a public buyer.

Prevailing Wage Responsibilities

Under New York Labor Law Article 8, including §224-d, contractors and subcontractors working on covered projects must:

  • Pay workers the prevailing wage and supplemental benefits for their specific trade and locality.
  • Maintain certified payroll records showing hours worked, job classifications, and wages paid.
  • Post the wage schedule at the job site in a visible location.
  • Cooperate with audits or investigations by the NYS Department of Labor (NYSDOL) or, in NYC, the Comptroller’s Office.

These requirements apply to laborers, mechanics, and tradespeople.

Exceptions to the Law

The Bureau of Prevailing Wage shall not enforce the prevailing wage requirements of §224-d when:

  • The project was solicited, contracted for, or work began, prior to October 1, 2021
  • The system has a capacity between 1 and 5 megawatts and was solicited, contracted for, or work began prior to July 5, 2022
  • The system has a capacity of less than 1 megawatt and is not a thermal energy network
  • The construction work is performed under a labor peace agreement, project labor agreement, or an enforceable agreement between an owner or contractor and a bona fide building and construction trade labor organization.

Conclusion

As clean energy construction expands across New York, prevailing wage requirements under Labor Law §224-d are increasingly shaping project planning and execution. With more mid-size systems now falling under its scope, especially those involving REC procurement by public entities like NYSERDA, contractors and developers must remain diligent in identifying when the law applies, understanding the appropriate prevailing wages, and maintaining proper records to stay compliant throughout the build.

Categories
blog

Energy Dominance Financing Prevailing Wage Requirements

Introduction

The Department of Energy’s newly expanded Energy Dominance Financing Program (EDF) is reshaping the U.S. energy‑infrastructure landscape, and with it, the compliance obligations for construction firms. As federal financing grows, so does the scrutiny on prevailing wage requirements, making 2026 a pivotal year for firms working on energy‑related projects. 

This guide breaks down the EDF, its legislative foundation, and how prevailing wage compliance takes effect in federally backed energy construction. 

What Is the Energy Dominance Financing Program?

The Energy Dominance Financing Program (EDF) is the rebranded and expanded successor to the Energy Infrastructure Reinvestment (EIR) Program under Section 1706 of the Energy Policy Act.

Legislative Basis 

  • The Department of Energy (DOE) implemented these changes through its Interim Final Rule, published October 28, 2025, in the Federal Register (90 FR 48705
  • The OBBBA amendments significantly broadened Section 1706, establishing EDF as a major federal financing mechanism for energy infrastructure 

Key EDF Features

  • Broader eligibility:
    • Projects that retool, repower, repurpose, or replace energy infrastructure, or increase capacity and reliability. 
    • Projects that enable operating energy infrastructure to avoid, reduce, utilize, or sequester air pollutants, including anthropogenic greenhouse gas emissions.
  • Applies to fossil, nuclear, clean energy, and critical‑minerals projects. 

Why Prevailing Wage Requirements Apply to EDF Projects

The EDF financing program can trigger Davis-Bacon Act (DBA) requirements through multiple means, including the following: 

  • DOE loan guarantees constitute federal financial assistance for construction.
  • Under DBA, federally financed construction projects must pay local prevailing wages to laborers and mechanics. 
  • DOE’s Interim Final Rule explicitly aligns EDF implementation with federal labor‑standards compliance requirements. 

What This Means for Firms 

If your project receives EDF financing, you must anticipate completing Davis-Bacon Act requirements, which include: 

  • Paying prevailing wages based on DOL wage determinations. 
  • Maintaining weekly certified payrolls. 
  • Ensuring proper worker classifications. 
  • Tracking fringe benefits accurately. 
  • Monitoring subcontractor compliance. 
  • Preparing for DOE and DOL audits. 

What’s at Stake

Failure to comply with the Davis-Bacon Act requirements can lead to several penalties, including: 

Common Mistakes 

Per the Department of Labor, common compliance issues on DBA projects include: 

  • Misclassification of laborers and mechanics. 
  • Failure to pay full prevailing wage, including fringe benefits, for all hours worked (including overtime hours). 
  • Incomplete or inaccurate recordkeeping, such as not counting all hours worked or not recording hours worked in each classification by an individual who worked in two or more classifications during a day. 
  • Failure to maintain a copy of the bona fide apprenticeship program and individual registration documents for apprentices. 
  • Failure to submit certified payrolls weekly. 
  • Failure to post the Davis-Bacon poster and applicable wage determination at the work site. 

Securing Compliance for EDF Projects with DBA Applicability 

As the EDF becomes a dominant force in U.S. energy financing, construction firms face new and unfamiliar compliance expectations. Our company specializes in prevailing wage consulting, helping contractors navigate the complexities of DBA, state wage laws, and federal financing requirements. Our support is built to meet the needs of your projects at any stage. If you’re curious about applying additional protection to your projects, feel free to reach out to learn more about our services.

Categories
blog

Illinois Shines & CEJA: Beyond the Basics of Prevailing Wage Compliance

The Climate and Equitable Jobs Act (CEJA) and the Illinois Shines program have reshaped renewable energy projects in Illinois, requiring contractors to pay prevailing wages and meet equity standards. For an introduction to CEJA, the Adjustable Block Program, and the Minimum Equity Standard, visit this blog for the full scope. Here, we address guidance on the practical compliance questions that arise during project execution. 

What documentation do I need to prove prevailing wage compliance?

Certified payroll reports are required, but they are only the starting point. Contractors must also maintain: 

  • Fringe benefit records: Proof of contributions to health, pension, and training funds. 
  • Itemized Wage Statements: Documentation to show rates of pay for straight time and overtime, along with deductions. 
  • Timecards and daily logs: Documentation that validates hours reported.
  • Worker classification logs: Evidence that employees are properly classified under county-specific wage determinations. 
  • Apprenticeship agreements: Records showing compliance with apprenticeship ratios. 
  • Subcontractor compliance records: Documentation verifying that lower tier subcontractors also meet prevailing wage obligations. 

Without these supporting documents, certified payroll reports alone will not withstand a governmental audit.

Are all subcontractors required to comply with prevailing wage requirements?

CEJA and Illinois Shines classify projects as “public works,” meaning all tiers of subcontractors must comply. All individual contractors are responsible for ensuring subcontractor compliance. These responsibilities include: 

  • Collecting certified payrolls from subcontractors. 
  • Auditing subcontractor records for accuracy. 
  • Including compliance clauses in subcontract agreements. 

Contractors that are not informed of the prevailing wage requirements on public works projects by a public body are still liable for the difference between the amount paid and the prevailing wage. If a contractor fails to notify a subcontractor of prevailing wage requirements, the contractor becomes liable for interest, penalties, or fines assessed by the IDOL (Illinois Department of Labor). The subcontractor is still, however, liable for paying the proper prevailing wage rate. 

What counts as a valid fringe benefit contribution under Illinois Shines & CEJA requirements?

Under Illinois law, contributions to health insurance, retirement plans, and trainingcontributions to registered apprenticeship programs qualify. These must be documented separately from wages. 

It is vital that contractors only take credit up to the amount listed in each column on the wage determination. For example, if a Carpenter classification has a $9.95 amount in the “H/W” (Health and Welfare) column, then $9.95 is the maximum amount the contractor can take credit for. So, even if a contractor is paying $15.00 in health insurance, they can only take credit for up to $9.95 for that classification. 

Prevailing wage rates are county-specific and updated monthly by the Illinois Department of Labor. Contractors must monitor updates throughout the project to avoid underpayment. Learn more about fringe benefits here

Apprenticeship and Training Requirements

CEJA emphasizes workforce development. Contractors must comply with apprenticeship utilization requirements, which means: 

  • Documenting ratios of apprentices to journeymen. 
  • Maintaining agreements with registered apprenticeship programs. • Ensuring apprentices are paid prevailing wage rates for their classification. 

The Minimum Equity Standard (MES)

Section 1‑75(c‑10) of the Illinois Power Agency Act requires the Illinois Power Agency (IPA) to create an Equity Accountability System, which includes the Minimum Equity Standard. 

The MES sets a required percentage of your project workforce that must be made up of Equity Eligible Persons (EEPs). This applies to: 

  • Approved Vendors and Designees participating in Illinois Shines
  • Companies bidding into Indexed REC procurements for utility‑scale renewable projects

The goal is simple: ensure that the clean energy boom in Illinois creates opportunities for workers who have historically been left out of these industries. 

Who Counts as an Equity Eligible Person (EEP)?

CEJA defines four categories of workers who qualify as EEPs. A worker is considered an EEP if they meet any of the following: 

1. Graduates or participants of state‑supported clean energy training programs 

This includes programs such as: 

  • Clean Jobs Workforce Network Program 
  • Clean Energy Contractor Incubator Program 
  • Illinois Climate Works Pre‑Apprenticeship Program 
  • Returning Residents Clean Jobs Training Program 
  • Clean Energy Primes Contractor Accelerator Program 
  • Solar training pipeline and multicultural jobs programs created under FEJA 

2. Individuals who are or were part of the foster care system 

3. Individuals who were formerly incarcerated 

4. Residents of an Equity Eligible Investment Community 

What Are the Audit and Enforcement Risks?

Contractors often wonder: What triggers an audit? Common triggers include:

  • Worker complaints.
  • Discrepancies in certified payroll reports. 
  • Random audits by the Illinois Department of Labor or local enforcement offices. 

Penalties for non-compliance include fines, withheld incentive payments, and potential debarment from future public works projects. 

How Are Incentives Affected by Compliance?

Prevailing wage compliance is directly tied to incentive eligibility under Illinois Shines. Failure to comply can result in: 

  • Loss of renewable energy credits (RECs). 
  • Disqualification from incentive payments. 
  • Reputational damage that impacts future bids. 
  • Ineligibility to participate in the Adjustable Block Program if found to no longer be an Approved Vendor. 

Conclusion

CEJA and Illinois Shines are transforming Illinois’ renewable energy landscape, but compliance is more than filing certified payroll reports. Contractors must maintain supporting documentation, monitor subcontractor compliance, track fringe benefits, and prepare for audits. With enforcement increasing, expert guidance is indispensable. 

Alliant Consulting bridges the gap between compliance management and contractor confidence, helping firms close projects with the assurance that prevailing wage obligations have been met. Partner now to secure assistance on your projects.