
blog


On June 6, 2026, the U.S. District Court for the District of Columbia vacated IRS Notice 2025-42 in full, ruling it "arbitrary and capricious" under the Administrative Procedure Act (APA). The decision in Oregon Environmental Council v. IRS, Civil Action No. 1:25-cv-04400 (CKK) (D.D.C. June 6, 2026), restored a beginning-of-construction framework just weeks before the OBBBA's July 4, 2026 beginning-of-construction deadline.
What does this mean for firms? For the roughly nine-month window between the ruling and the July 4, 2026 deadline, developers had two paths to establish beginning of construction rather than one. Projects that didn't lock in a beginning-of-construction position by that date now proceed on the December 31, 2027 placed-in-service pathway instead. Either way, prevailing wage and apprenticeship (PWA) compliance remains a separate, ongoing requirement regardless of which beginning-of-construction method a project used.
The Inflation Reduction Act of 2022 (Pub. L. 117-169) added Sections 45Y and 48E to the Internal Revenue Code as technology-neutral successors to the older Section 45 production tax credit and Section 48 investment tax credit. Section 45Y provides a production tax credit for electricity generated at a "qualified facility" with a greenhouse gas emissions rate of zero or below; Section 48E provides an investment tax credit based on a taxpayer's qualified investment in such a facility. Both credits apply to facilities placed in service after December 31, 2024.
Neither the IRA nor the OBBBA defines "beginning of construction" in the statutory text. Instead, the IRS has filled that gap through a long series of sub-regulatory notices dating back to Notice 2013-29, which first established the two methods described below. That framework was reaffirmed and extended across more than a decade of subsequent guidance, including Notice 2022-61, which applied the same principles to Sections 45Y and 48E, and, importantly, to the prevailing wage and apprenticeship (PWA) rules discussed later in this post.
"Beginning of construction" matters because it is the trigger date used throughout federal energy tax credit law to determine which set of rules, and which deadlines, apply to a given project.
Physical Work Test. Construction begins when "physical work of a significant nature" starts. This is a qualitative, facts-and-circumstances test. It focuses on the nature of the work, not its cost or quantity, and covers both on-site work (e.g., excavating a foundation, setting anchor bolts, installing racking) and off-site work performed under a binding written contract (e.g., manufacturing of components, mounting equipment, transformers). Preliminary activities, like planning, permitting, site clearing, and geotechnical testing do not count.
Five Percent Safe Harbor. Construction is deemed to have begun once a taxpayer pays or incurs 5% or more of the total cost of the facility. This is a quantitative, bright-line test that lets developers establish eligibility through early-stage spending, such as procurement or deposits, without needing to show that physical construction activity has actually started on-site.
Both methods have historically been subject to a Continuity Requirement: the taxpayer must maintain continuous progress toward completion, which is generally deemed satisfied under a Continuity Safe Harbor if the facility is placed in service within four calendar years of the year construction began.
On July 7, 2025, President Trump issued Executive Order 14315, Ending Market Distorting Subsidies for Unreliable, Foreign-Controlled Energy Sources (90 Fed. Reg. 30,821). The order directed the Treasury Department, within 45 days of the OBBBA's enactment, to issue guidance ensuring that the OBBBA's credit termination provisions for wind and solar were "strictly" enforced, including guidance to prevent taxpayers from using broad safe harbors to establish beginning-of-construction status without having actually built a substantial portion of the facility.
In response, the IRS issued Notice 2025-42 on August 15, 2025. The notice:
Source: IRS Notice 2025-42, 2025-36 I.R.B. 351 (full text, IRS.gov).
Seven governmental, tribal, and private organizations, including the Oregon Environmental Council, sued the IRS, arguing that Notice 2025-42 was arbitrary and capricious under the APA. Seventeen states and the District of Columbia also filed an amicus brief in support of the plaintiffs, arguing the notice would raise electricity costs and disrupt state energy planning.
Source: Amicus Curiae Brief of Oregon et al., Case No. 1:25-cv-04400-CKK, Doc. 29 (D.D.C. Feb. 20, 2026) (full text).
On June 6, 2026, Judge Colleen Kollar-Kotelly of the U.S. District Court for the District of Columbia granted the plaintiffs' motion for summary judgment and vacated Notice 2025-42 in full, remanding the matter to the IRS. The court held that the IRS had failed to satisfy the "reasoned decision-making" standard required of federal agencies under Motor Vehicle Manufacturers Association v. State Farm Mutual Automobile Insurance Co., 463 U.S. 29 (1983).
With Notice 2025-42 vacated, the pre-existing framework under Notice 2022-61 and its predecessor notices is restored. Wind and large-scale solar developers may once again use either the Physical Work Test or the Five Percent Safe Harbor to establish beginning of construction ahead of the July 4, 2026 deadline.
Two deadlines remain unchanged by the ruling and are worth keeping straight:
As of this writing (July 13, 2026), the July 4 deadline has passed, and this remains a live legal question rather than settled law:
Given this, several firms tracking the case advised developers not to abandon Physical Work Test documentation even if they qualified under the Five Percent Safe Harbor in the run-up to the deadline, since a later reversal on appeal could still leave safe-harbor-only projects exposed retroactively.
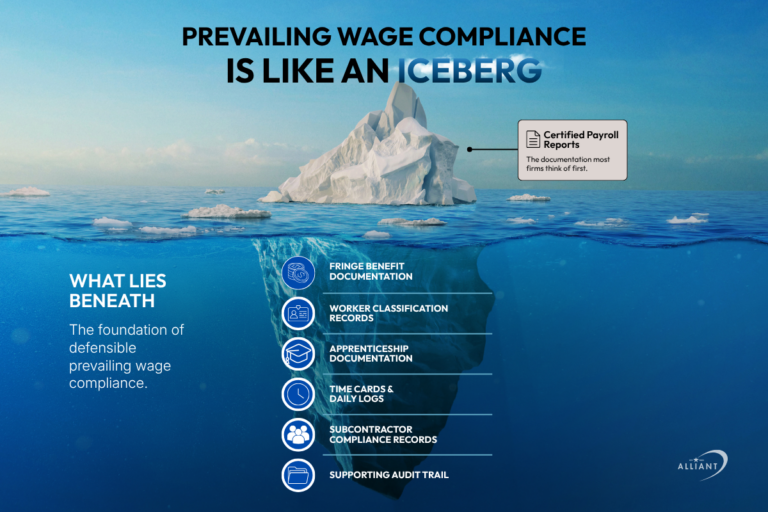
Whichever beginning-of-construction method your project ultimately relies on, prevailing wage and apprenticeship compliance is a separate, independent requirement that determines whether you receive the base credit rate or the enhanced rate — generally five times higher — under Sections 45Y and 48E. That determination is not affected by Oregon Environmental Council v. IRS. With that in mind, firms should consider the following:
The vacatur of Notice 2025-42 is a meaningful change for wind and solar developers racing toward the July 4, 2026 beginning-of-construction deadline. It restores optionality that many projects were built around, but the government's potential for evolution in the legal landscape means rulings could still shift past the deadline.
What remains applicable is the importance of rigorous, well-documented prevailing wage and apprenticeship compliance. Building the foundation for securing the full value of the 45Y and 48E credits is key, regardless of how the begin-construction question is ultimately resolved.
Have questions about how this affects your project's compliance strategy? Connect with our team to make sure your prevailing wage and apprenticeship documentation is airtight, regardless of which safe harbor you rely on to establish beginning of construction.
blog

blog
blog
blog
blog
blog